Pass the Phone, Not the Resentment: Twelve UK Payment Apps Face a Sunday Lunch Bill
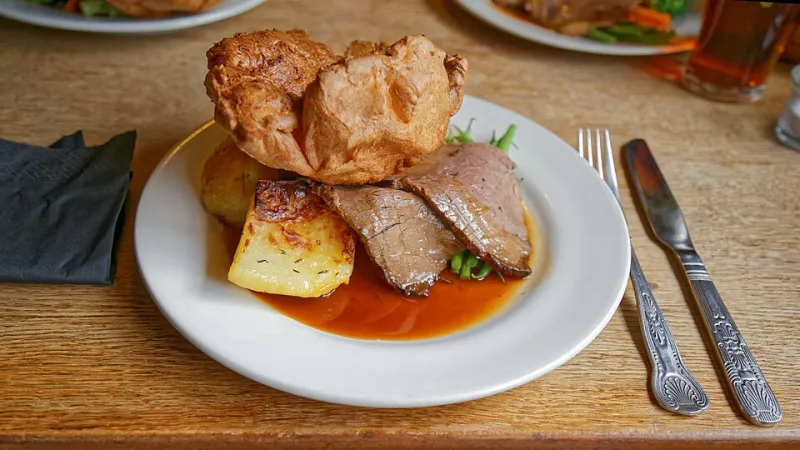
Photo: Acabashi, CC BY-SA 4.0, via Wikimedia Commons
Sunday lunch is a lovely idea right up until the bill lands. On a cold November Sunday in 2026, eight of us sat around a scratched oak table in a Leeds pub, pleasantly full of beef, Yorkshire puddings and the kind of gravy that justifies a second trip to the carvery. The bill came to £612.40. Of that, £87.40 was a knot of contested extras: three additional Yorkshires, two flat whites, one sticky toffee pudding that was definitely shared, and a round of lime sodas nobody would own up to ordering.
The maths was not the problem. The audience was. Splitting a bill is a small social performance: someone has to ask, someone has to look keen, someone has to say they will sort it later, and someone has to decide whether to chase. We took twelve UK payment and bill-splitting apps through that exact lunch to see which ones reduced the friction and which ones quietly added to it.
The setup: one table, eight people, too many opinions
We used each app’s native request or split function where one existed, and a plain bank transfer with a reference where it did not. We did not use cash, because nobody had any. We did not use a spreadsheet, because this was supposed to be lunch. Two of the eight had already left by the time the card machine arrived, which is either bad manners or a realistic test condition depending on your view.
The bill included a 10% service charge. We left it on. That decision alone caused more discussion than any app interface.
What we measured, and why fees are only half the story
We timed five things. Request speed: how long from the bill landing to a payment request appearing on someone else’s phone. Fees: any charge to sender or recipient, and how clearly it was flagged before the final tap. Reminder etiquette: whether a nudge could be scheduled, softened or cancelled, and whether the default felt polite or passive-aggressive. Group visibility: who could see the amounts, the names and the payment status. And the deferred-payment problem: how gracefully each app handled the moment someone said, with great confidence, that they would sort it later.
Here is the short version of what we found. Ratings are for this test, not for all time.
| App | Request speed | Fee clarity | Reminder etiquette | Group visibility | Handles ‘later’ |
|---|---|---|---|---|---|
| Monzo | Fast | Clear | Gentle | Partial | Yes |
| Starling | Fast | Clear | Gentle | Partial | Yes |
| Revolut | Fast | Clear | Adjustable | Open | Yes |
| Wise | Medium | Clear | Gentle | Partial | Clunky |
| PayPal | Medium | Murky | Blunt | Open | No |
| Splitwise | Tracker only | Clear | Adjustable | Open | Yes |
| NatWest | Medium | Clear | None | Closed | No |
| Lloyds | Medium | Clear | None | Closed | No |
| Barclays | Medium | Clear | None | Closed | No |
| HSBC | Slow | Clear | None | Closed | No |
| Santander | Slow | Clear | None | Closed | No |
| Chase UK | Fast | Clear | Gentle | Partial | Yes |
The fast ones: speed without sting
Monzo, Starling, Revolut and Chase UK produced a request link in under half a minute. That matters more than it sounds. The longer the gap between the bill and the request, the easier it is for the group to drift into vague promises. A request that arrives while everyone is still at the table feels like part of the meal, not a follow-up invoice.
Revolut gave the most control. We could set individual amounts, add a note explaining the £87.40 extras, and choose a reminder schedule that did not feel like a debt collector. Monzo and Starling were quicker to use but less flexible on the reminder tone. Chase UK was similarly brisk and clean, though the group view was thinner: you could see who had paid, but not the whole story of why the numbers were what they were.
Wise was fine once we got going, but the request flow took longer to set up than the others. In a group of eight, two extra taps per person becomes a small admin project.
The fee question: pennies that change the mood
Most of the apps we tested did not charge for a straightforward UK transfer. That is the good news. The less good news is that fee clarity varied. PayPal’s request flow was the least clear of the dozen: the wording around fees appeared late enough that two people at the table asked whether they were paying more than they owed. They were not, in the end, but the uncertainty did its own damage. A fee you cannot see is a fee everyone assumes is there.
Splitwise does not move money at all, which is both its strength and its limit. It solved the maths beautifully, showed everyone exactly who owed what, and then left us to make the actual payments elsewhere. As a social object, it was excellent. As a payment app, it was a very well-organised clipboard.
Reminders: the difference between a nudge and a nag
The high street banking apps — NatWest, Lloyds, Barclays, HSBC and Santander — mostly left reminders to us. We sent manual texts with references like ‘roast + tip’. That worked, but it made the organiser the bad guy. One person at the table said they preferred it because it felt more personal. Another said it felt like being chased by a mate who had taken the role far too seriously.
Revolut and Splitwise were the only two that let us adjust the reminder cadence without a fight. Monzo, Starling and Chase UK sent gentle default reminders that most people ignored politely. PayPal’s reminders felt the most transactional, which is a strange thing to say about a payment app but accurate.
Group visibility: who can see what, and who feels watched
Open group views are not universally welcome. Revolut and Splitwise showed everyone the full picture: amounts, names, who had paid and who had not. That reduced suspicion. It also created a small theatre of accountability. One person paid before the puddings were cleared, partly, I suspect, because the app made not paying visible.
The high street apps offered the opposite: a one-to-one request with no shared view. That is more private, but it puts the organiser in charge of the truth. If you are the one who has to say ‘actually, you owe £18.40, not £15’, you want a screen that backs you up.
The ‘I’ll sort it later’ problem
The best apps made ‘later’ a legitimate state rather than a social failure. Revolut and Splitwise let us mark someone as paying later without an immediate follow-up. Monzo, Starling and Chase UK handled it with a light touch: the request stayed visible, but the app did not escalate into nagging. Wise was clunky here; the deferred state was not obvious, so we ended up sending a manual message anyway.
With the high street apps, ‘later’ meant the organiser kept a mental list. That list is where resentment lives. It is also where the £87.40 went from a shared joke to a slightly tired conversation at 9pm.
The verdict: fewer taps, fewer speeches
No app made eight people generous. The best ones made the awkward bit shorter. If you split bills regularly, a fast request app with a clear group view is worth more than a fancy one with a fee you have to hunt for. If your group is chaotic, a tracker like Splitwise plus a quick payment app is probably the most honest combination: one place for the truth, one place for the money.
At the end of our lunch, seven of eight had paid before the plates were cleared. The eighth paid at 11.42pm with a message that said ‘sorry, been at the pub’. The app did not make that happen. But it did mean nobody had to send the message asking why.